
ONEE Stock Note 22 สิงหาคม 2565
ก่อนไปคิดอะไร เราได้เข้าร่วมการประชุมนักวิเคราะห์หลังจากการประกาศงบ 2Q65 เพื่อทราบถึงทิศทางผลประกอบการในช่วง 2H65 รวมถึงการฟื้นตัวของภาพอุตสาหกรรมโฆษณาผ่านของทาง TV ภายหลังจากการที่ตัวเลขเงินเฟ้ออยู่ในระดับสูงซึ่งกระทบในเรื่องของกำลังซื้อของผู้บริโภค ซึ่งรายได้จากโฆษณาส่วนนี้คิดเป็น 52% ของรายได้รวมใน 2Q65 | |
|---|---|
หลังไปได้อะไร ภาพรวมเม็ดเงินโฆษณาผ่านช่องทาง TV ในช่วง 1H65 ติดลบ 1% YoY จากผลกระทบทางด้านเศรษฐกิจทำให้ลูกค้ายังขาดความมั่นใจในการใส่เม็ดเงินโฆษณาเข้าไป โดยผู้บริหารแจ้งว่าในช่วง 3Q65 ยังไม่เห็นสัญญาณของการฟื้นตัวเนื่องจากภาพรวมเศรษฐกิจยังคงอ่อนแอ โดยคาดหวังว่าจะเริ่มเห็นการฟื้นตัวในช่วง 4Q65 กลยุทธ์ของบริษัทในสถานการณ์เช่นนี้ คือ พยายามสร้าง Content ที่ดีอย่างต่อเนื่อง เพื่อเพิ่ม Rating ให้กับช่องของตัวเอง ซึ่งคาดหวังว่าพอวันที่เม็ดเงินโฆษณากลับมาบริษัทจะได้รับส่วนแบ่งจากเม็ดเงินก้อนนี้ที่มากขึ้น รวมถึงมีโอกาสปรับขึ้นค่าโฆษณาได้ด้วย โดยล่าสุด Rating ของช่อง ONE ในช่วงเวลา Prime time ขึ้นมาอยู่อันดับ 2 แซงช่อง 3 ขึ้นมาเรียบร้อยแล้ว แต่ถ้าดู Rating แบบ All day จะอยู่ในอันดับ 3 ยังคงเป็นรองช่อง 3 แต่อย่างไรก็ตาม 70% ของรายได้โฆษณาผ่านช่องทาง TV ของบริษัทนั้นเกิดจากช่วง Prime time | |
ส่วนธุรกิจอื่นๆ ปัจจุบันได้มีการคุยกับ OTT Platform อยู่ 2 ราย โดยหนึ่งในนั้น คือ Amazon prime ที่ได้มีการเซ็นต์สัญญาไว้แล้วแต่ปัจจุบันกำลังคุยในเรื่องรายละเอียดของ Project ส่วนอีกเจ้าเป็นบริษัทจากประเทศสหรัฐฯ แต่ภาพรวมของรายละเอียดนั้นยังไม่ชัดเจน โดยคาดว่ายังไม่เห็นในเชิงของรายได้จากส่วนนี้ที่จะเข้ามาในช่วง 2H65 สำหรับภาพเป้าหมายทางการเงินในปีนี้ ทางผู้บริหารยังคงตั้งเป้าการเติบโตของรายได้ที่ 10%YoY แต่อย่างไรก็ตาม ด้วยกลยุทธ์ของบริษัทที่พยายามจะสร้าง Content ดีๆ เพื่อเพิ่ม Rating ให้กับช่องอย่างต่อเนื่องทำให้ในเชิงของต้นทุนคาดจะยังคงได้รับแรงกดดันในช่วง 2H65 ทำให้เราคาดว่ากำไรช่วง 2H65 จะใกล้เคียงกับช่วง 1H65 ความเห็นและกลยุทธ์การลงทุน กำไรสุทธิ 1H65 คิดเป็นเพียง 44% ของประมาณการทั้งปี บวกกับ 2H65 ภาพกำไรมีแนวโน้มจะฟื้นตัวช้ากว่าที่คาดไว้ก่อนหน้า เพื่อยึดหลักระมัดระวังเราจึงมีการปรับลดประมาณการปีนี้ 15% แต่ยังคงประมาณการตั้งแต่ปี 2566 โดยภายใต้ประมาณการใหม่คาดปี 2565 ONEE จะมีกำไรอยู่ที่ 831 ลบ. ทรงตัว YoY ก่อนจะพลิกเติบโตเด่น 32%YoY ในปี 2566 จากภาพรวมเม็ดเงินโฆษณาที่คาดว่าจะเริ่มเห็นการฟื้นตัวได้ ช่วง 4 เดือนที่ผ่านมาพบราคาหุ้น ONEE ปรับตัวลดลง 26.5% ซึ่งเรามองสะท้อนภาพผลการ | |
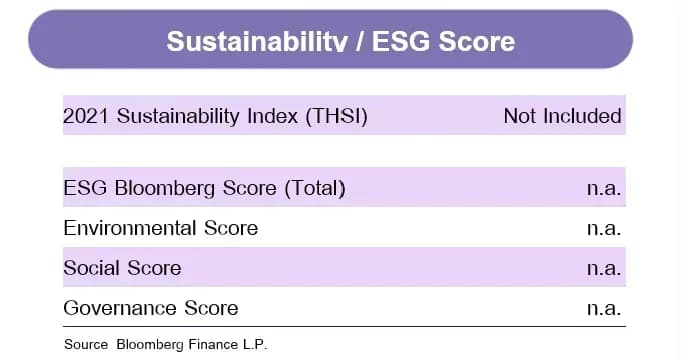
EGS Disclosure Score
2020 | 2021 | |
|---|---|---|
ESG Disclosure Score | n.a | n.a |
Environment | n.a | n.a |
Total GHG Emissions (thousands of metric tonnes) | n.a | n.a |
Total Water Use (thousands of cubic meters) | n.a | n.a |
Hazardous Waste (thousands of metric tonnes) | n.a | n.a |
Total Waste (thousands of metric tonnes) | n.a | n.a |
Social | n.a | n.a |
|---|---|---|
Number of Employees | n.a | n.a |
Workforce Accidents | n.a | n.a |
Lost Time from Accidents | n.a | n.a |
Fatalities - Contractors | n.a | n.a |
Fatalities - Employees | n.a | n.a |
Fatalities - Total | n.a | n.a |
Community Spending | n.a | n.a |
Governance | n.a | n.a |
|---|---|---|
Size of the Board | n.a | n.a |
Indep Directors | n.a | n.a |
% Indep Directors | n.a | n.a |
Board Duration (Years) | n.a | n.a |
# Board Meetings | n.a | n.a |
Board Mtg Attendance (%) | n.a | n.a |
Source: Bloomberg Finance L.P. as of 2021
Disclaimer
การจัดทำข้อมูลด้านสิ่งแวดล้อม สังคมและการกำกับดูแลกิจการที่ดี (Environmental Social Governance หรือ ESG) เป็นการทำข้อมูลและเปิดเผยโดยบริษัท Bloomberg ซึ่งมีการทำข้อมูลด้านสิ่งแวดล้อม ด้านสังคม และด้านธรรมภิบาล อาทิเช่นข้อมูลการใช้พลังงานที่สะท้อนต้นทุน ความเสี่ยงในการพึ่งพาพลังงานของธุรกิจ ความเสี่ยงด้านการทำงานที่อาจจะเกิดจากอุบัติเหตุ รวมถึงสัดส่วนของคณะกรรมการบริหาร ตั้งแต่ปี 2010 และขึ้นอยู่กับการเปิดเผยข้อมูลของแต่ละบริษัท
Financial Statement
Profit and Loss Statement
FY December 31 | Unit | 2Q64 | 3Q64 | 4Q64 | 1Q65 | 2Q65 |
|---|---|---|---|---|---|---|
Total revenue | (Btmn) | 1,394 | 1,086 | 1,524 | 1,572 | 1,490 |
Cost of goods sold | (Btmn) | (637) | (522) | (791) | (856)) | (832) |
Gross profit | (Btmn) | 757 | 564 | 734 | 716 | 659 |
SG&A | (Btmn) | (414) | (371) | (521) | (435) | (450) |
Other income/expense | (Btmn) | 19 | 23 | 22 | 16 | 46 |
Interest expense | (Btmn) | (37) | (35) | (19) | (7) | (3) |
Pre-tax profit | (Btmn) | 325 | 181 | 216 | 290 | 252 |
Corporate tax | (Btmn) | (62) | (12) | (13) | (41) | (73) |
Equity a/c profits | (Btmn) | 5 | 0 | 0 | 2 | 3 |
Minority interests | (Btmn) | (1) | (1) | 2 | 1 | (0) |
Core profit | (Btmn) | 262 | 168 | 205 | 250 | 179 |
Extra-ordinary items | (Btmn) | 0 | 0 | 0 | 0 | 0 |
Net Profit | (Btmn) | 262 | 168 | 205 | 250 | 179 |
EBITDA | (Btmn) | 396 | 250 | 271 | 334 | 397 |
Core EPS | (Bt) | 0.11 | 0.07 | 0.09 | 0.11 | 0.08 |
Net EPS | (Bt) | 0.11 | 0.07 | 0.35 | 0.46 | 0.52 |
Source: Company data, SCBS Wealth Research
2Q65 Earnings Reviews
FY December 31 (Btmn)2Q643Q644Q641Q652Q65%YoY%QoQTotal revenue1,3941,0861,5241,5721,49017.1 3.1 Cost of goods sold (637)(522)(791)(856)(832)24.58.2Gross profit7575647347166599.2 (2.4)SG&A (414)(371)(521)(435)(450)8.5 (16.4)Other income/expense19 23 22 16 46 (40.5) (25.3)Interest expense(37)(35)(19)(7)(3)(82.4)(65.6)Pre-tax profit325 181 216 290 252 18.9 34.6 Corporate tax(62)(12)(13)(41)(73)(19.8)227.8 Equity a/c profits(1)(1)2 1 (0)(703.6)(54.9Minority interests(0)(0)(0)0(0)(650.0)(136.0)Core profit262 168 205 250 1,490179 17.1 29.7 3.1 21.9 Extra-ordinary items 0 0000Net Profit262 168 205 250 179 29.7 21.9 EBITDA 396 2502713343975.023.1 Core EPS(Bt)0.11 0.07 0.09 0.11 0.08 29.7 21.9 Financial Ratio (%) Gross margin 54.3 51.9 48.145.5 44.2 (6.7)(5.4)SG&A/Revenue 29.7 34.2 34.2 27.7 30.2 (7.3)(18.9)EBITDA margin28.4 23.117.8 21.2 26.6 (10.3)19.4 Net profit margin 18.8 15.5 13.5 15.9 12.0 10.8 18.2 Source: Company data, SCBS Wealth ResearchFinancial StatementProfit and Loss Statement FY December 31 Unit 2563 2564 2565F 2566F 2567F Total revenue (Btmn) 3,127 5,347 5,924 6,516 7,168 Cost of goods sold (Btmn) (1,540) (2,637) (3,248) (3,510) (3,854) Gross profit (Btmn) 1,587 2,710 2,676 3,006 3,314 SG&A (Btmn) (925) (1,707) (1,777) (1,857) (2,014) Other income/expense (Btmn) 89 91 130 154 164 Interest expense (Btmn) (87) (129) (15) (13) (11) Pre-tax profit (Btmn) 664 965 1,013 1,290 1,452 Corporate tax (Btmn) (38) (137) (182) (194) (128) Equity a/c profits (Btmn) 5 0 02 3 Minority interests (Btmn) (0) (0) (0) (0) (0) Core profit (Btmn) 631 828 831 1,098 1,237 Extra-ordinary items (Btmn) 0 0 0 0 0 Net Profit (Btmn) 631 828 831 1,098 1,237 EBITDA (Btmn) 856 1,236 1,173 1,458 1,627 Core EPS (Bt) 0.33 0.35 0.35 0.46 0.52 Net EPS (Bt) 0.33 0.35 0.35 0.46 0.52 DPS (Bt) 0.00 0.07 0.14 0.18 0.21 Source: Company data, SCBS Wealth Research Balance Sheet FY December 31 Unit 2563 2564 2565F 2566F 2567F Total current assets (Btmn) 2,262 4,294 4,860 5,627 6,457 Total fixed assets (Btmn) 5,293 5,011 5,019 5,198 5,280 Total assets (Btmn) 7,555 9,305 9,969 10,825 11,737 Total loans (Btmn) 655 378 317 257 197 Total current liabilities (Btmn) 2,001 2,037 2,040 2,135 2,253 Total long-term liabilities (Btmn) 3,451 423 416 411 407 Total liabilities (Btmn) 5,452 2,460 2,456 2,546 2,660 Paid-up capital (Btmn) 3,810 4,452 4,452 4,452 4,452 Total equity (Btmn) 2,102 2,049 398 609 658 Cash Flow Statement FY December 31 Unit 2563 2564 2565F 2566F 2567F Core Profit (Btmn) 631 828 831 1,098 46.2 Depreciation and amortization (Btmn) 100 142 144 153 161 Operating cash flow (Btmn) 703 1,533 832 1,209 1,364 Investing cash flow (Btmn) (2,096) (98) (200) (200) (200) Financing cash flow (Btmn) 1,608 615 (234) (400) (506) Net cash flow (Btmn) 215 2,049 398 609 658 Key Financial Ratios FY December 31 Unit 2563 2564 2565F 2566F 2567F Gross margin (%) 50.8 50.7 45.2 46.1 46.2 Operating margin (%) 21.2 18.8 15.2 17.6 18.1 EBITDA margin (%) 27.4 23.1 19.8 22.4 22.7 EBIT margin (%) 24.0 20.5 17.4 20.0 20.4 Net profit margin (%) 20.2 15.5 14.0 16.9 17.3 ROE(%) 30.0 12.1 11.1 13.3 13.6 ROA(%) 8.4 8.9 8.3 10.1 10.5 Net D/E (x) 1.6 (0.3) (0.3) (0.4) (0.4) Interest coverage (x) 8.7 8.5 68.0 100.0 133.0 Debt service coverage (x) 1.2 2.4 3.5 5.4 7.8 Core PER (x) 28.8 27.5 27.4 20.7 18.4 PBV (x) 8.73.33.02.72.5Payout Ratio (%) 0.0 19.8 40.0 40.0 40.0 Main AssumptionFY December 31 Unit 2563 2564 2565F 2566F 2567F Sales Growth (%YoY) 16.171.010.8 10.0
10.0SG&A/Sales (%) 21.2 18.8 15.2 17.6 28.1 Source: Company data, SCBS Wealth Research